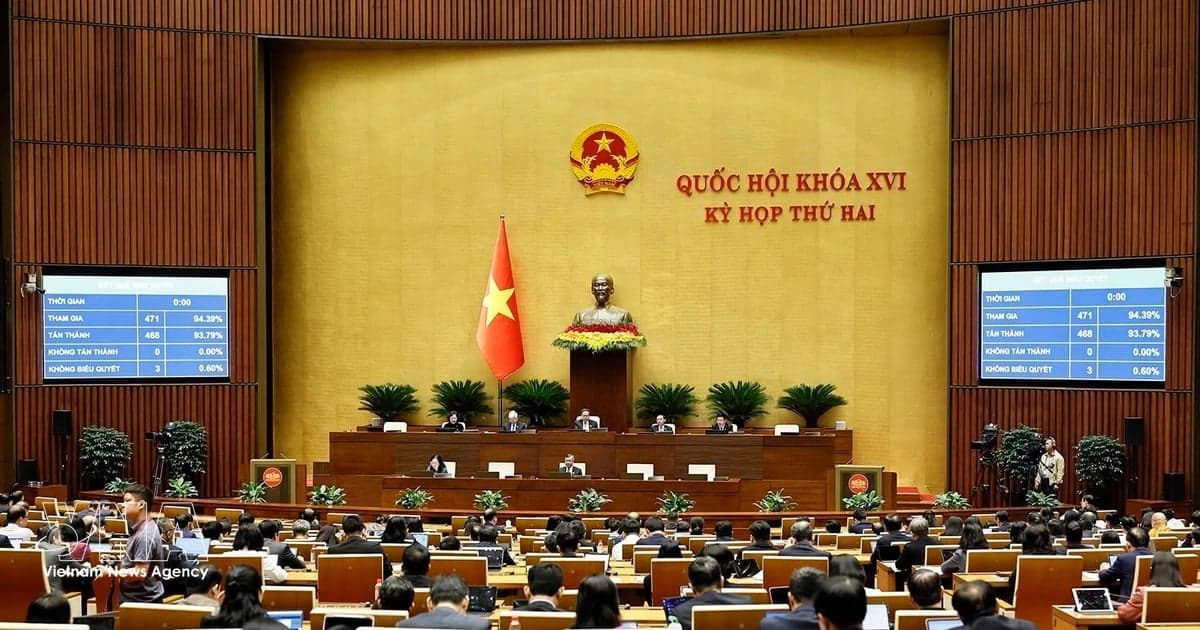
Vietnam's National Assembly on November 20 adopted two laws amending tax and investment regulations.
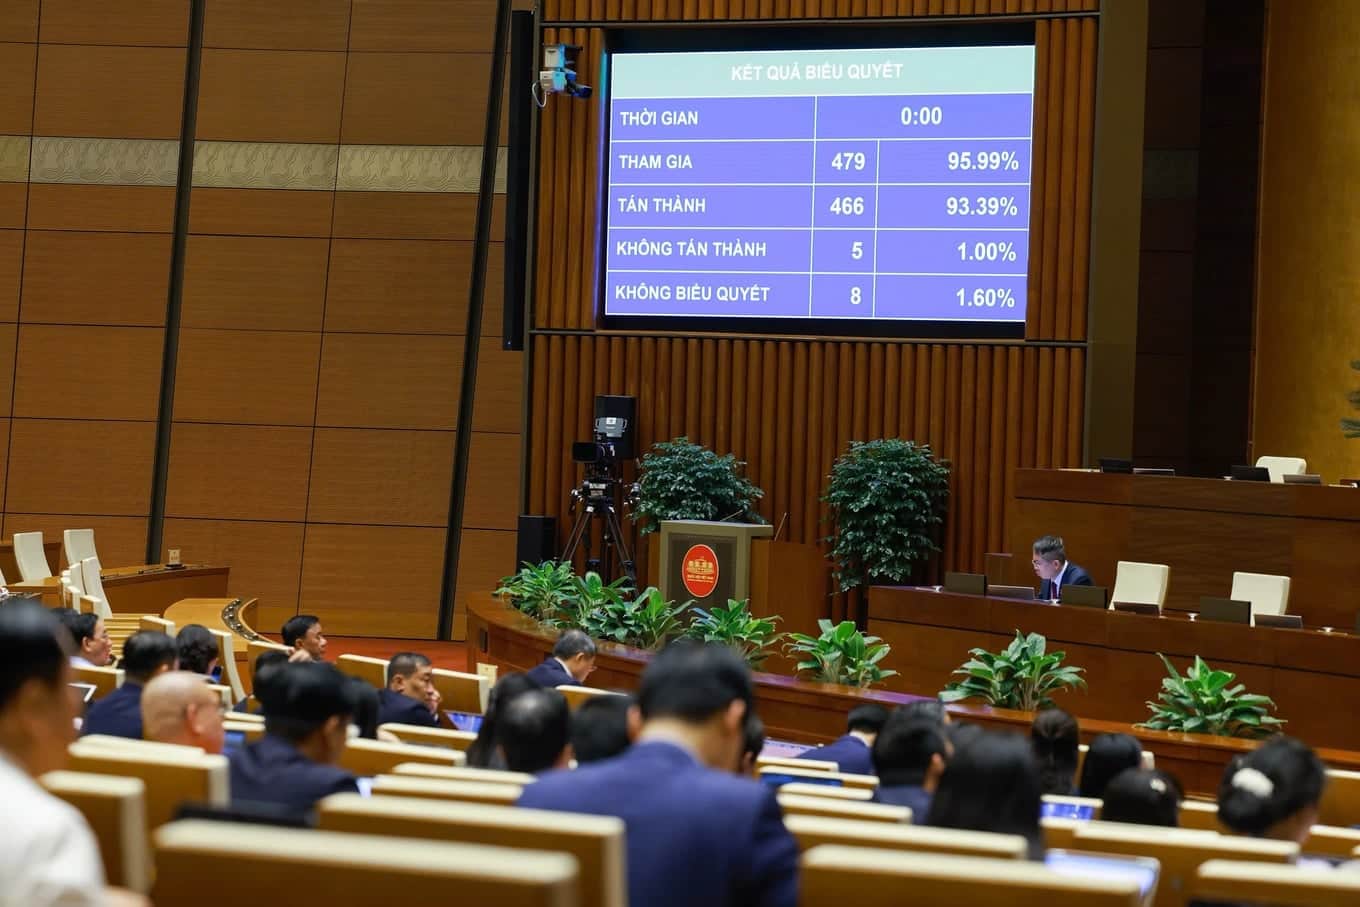
The law amending several articles of the laws on corporate income tax, non-agricultural land use tax and personal income tax was approved by 475 of the 477 deputies present.
Minister of Finance Ngo Van Tuan said the law added corporate income tax exemptions for public educational institutions and non-profit private schools in line with Political Bureau Resolution No. 71-NQ/TW. The exemption will apply only to income directly related to education and training, scientific research and educational support services.
The law also exempts businesses and individuals providing meals to educational and medical establishments from corporate and personal income taxes. The measure supports education and healthcare in line with Political Bureau Resolutions No. 71-NQ/TW and No. 72-NQ/TW.
The amendments introduce tax incentives for small and medium-sized enterprises. The annual revenue threshold for choosing a tax calculation method will rise from 3 billion VND to 10 billion VND, and newly established SMEs will receive a three-year corporate income tax exemption.
Businesses will be allowed to deduct expenses for training, technical consultancy, product improvement and technology transfer provided by large enterprises to SMEs in their value chains. Enterprises employing large numbers of workers with disabilities or from ethnic minority groups will receive tax reductions equal to additional spending on those employees.
The three-year exemption will not cover businesses established through mergers, consolidations, divisions or conversions, or new enterprises formed after another business with the same owners or controlling shareholders is dissolved.
Land used for education and training, as well as residential land within prescribed limits owned by ethnic minority households and individuals in ethnic and mountainous areas, will be exempt from non-agricultural land use tax.
Abandoned land will be subject to a 0.2% tax rate, while land used for purposes other than those approved will face a 0.15% rate. The period for stabilising taxable land prices will be reduced from five years to three years.
Resident individuals providing meals to educational and medical establishments will be exempt from personal income tax. Individual business operators with annual revenue of up to 10 billion VND may choose to pay tax based on income or taxable revenue.
The amended law comprises four articles and will take effect on January 1, 2027, except for certain provisions. The new revenue threshold will apply from the 2027 tax year, the tax on abandoned land from July 1, 2027, and revised land price provisions from January 1, 2028.
The amended Investment Law gives the authority responsible for issuing investment conditions the authority to decide on their relaxation. The Government will be authorised to approve special investment incentive and support packages within its jurisdiction.
If a package requires changes to existing laws or resolutions, the Government will submit proposals under simplified procedures. The packages target particularly important projects with significant socio-economic impacts, developed through negotiations with strategic investors and requiring swift policy responses.
The revised law clarifies special investment procedures on land allocation and leasing and specifies conditions and mechanisms for accelerated depreciation incentives for green projects.
The law amending certain articles of the Investment Law comprises three articles and will take effect on March 31, 2027, except for provisions specified in Points a, b, c and d, Clause 1, Article 2.
Sources: VietnamPlus / Vietnam News Agency