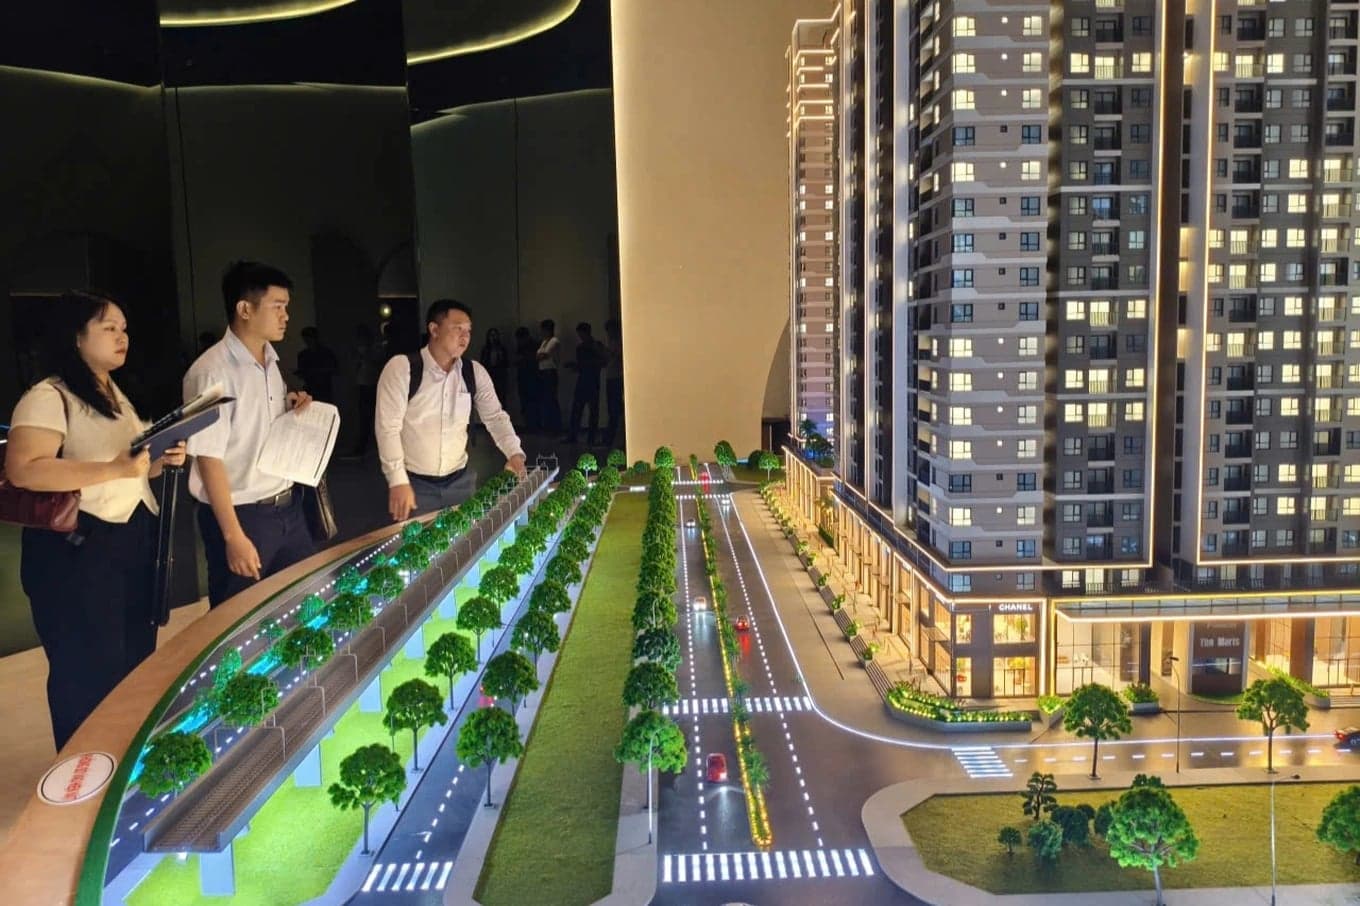
The average listed price of primary-market apartments in Ho Chi Minh City before the administrative merger was about VND 102 million per square metre in the third quarter, 39% below the previous quarter and 26% below the third quarter of 2025, according to Cushman & Wakefield. The decline came after several years of rising prices.
Why the average price fell without a broad price drop
The research firm attributed the change to the structure of new supply. Ho Chi Minh City recorded 2,373 newly launched apartments, up 87% from the previous quarter and nearly four times the figure from the same period last year. All new supply was outside central areas: 51% in the east, 35% in the south and 14% in the west. There were no launches in central or near-central areas.
Central projects usually cost much more than those on the outskirts, so their absence pulled down the market average without making existing projects suddenly cheaper. Developers were also more cautious about pricing and launch timing. The reported prices are base list prices excluding discounts and payment incentives.
High-end homes dominate while buyers remain cautious
Affordable options remain limited. High-end apartments made up 54% of new supply, luxury homes 30% and ultra-luxury homes 2%, meaning 86% was high-end or above and 14% was mid-range. Transactions were concentrated in projects below VND 100 million per square metre with convenient transport and clear legal status.
Even that price is difficult for many buyers. A 60-square-metre apartment at VND 80 million per square metre costs VND 4.8 billion before taxes, fees and possible finishing costs. About 1,890 apartments were absorbed in the third quarter, or 37% of primary supply including earlier launches. Savills reported about 5,800 primary apartments, around 1,400 transactions, a 25% absorption rate, and 45% for new launches.
Both reports show rising supply and cautious demand. A Cushman & Wakefield survey of 11 banks found an average fixed mortgage rate of about 10.9% a year for 12 to 24 months. Cao Thi Thanh Huong of Savills said high rates were pressuring developers' cash flow and buyers' ability to pay. Savills said projects with varied products and flexible, longer payment terms sold better because they reduced the initial payment.
Will more supply give buyers more options?
The 39% fall does not yet show a broad price decline, but more supply gives buyers more choices. Developers may compete through terms, schedules and discounts. A discount or payment extension does not reduce total ownership costs by the same amount, so buyers must calculate the final price, full-term interest, extra fees and payments after interest support ends.
Cushman & Wakefield forecasts more than 27,000 new apartments from the fourth quarter through the end of 2027, averaging over 5,000 per quarter, twice the third-quarter launch volume. Savills forecasts about 6,000 apartments in the final quarter of 2026, nearly 30% below its initial forecast because some projects were delayed. Competition may grow where several similar projects are sold. Demand for homes to live in remains, but affordable products are still limited.
Sources: Dân Trí