
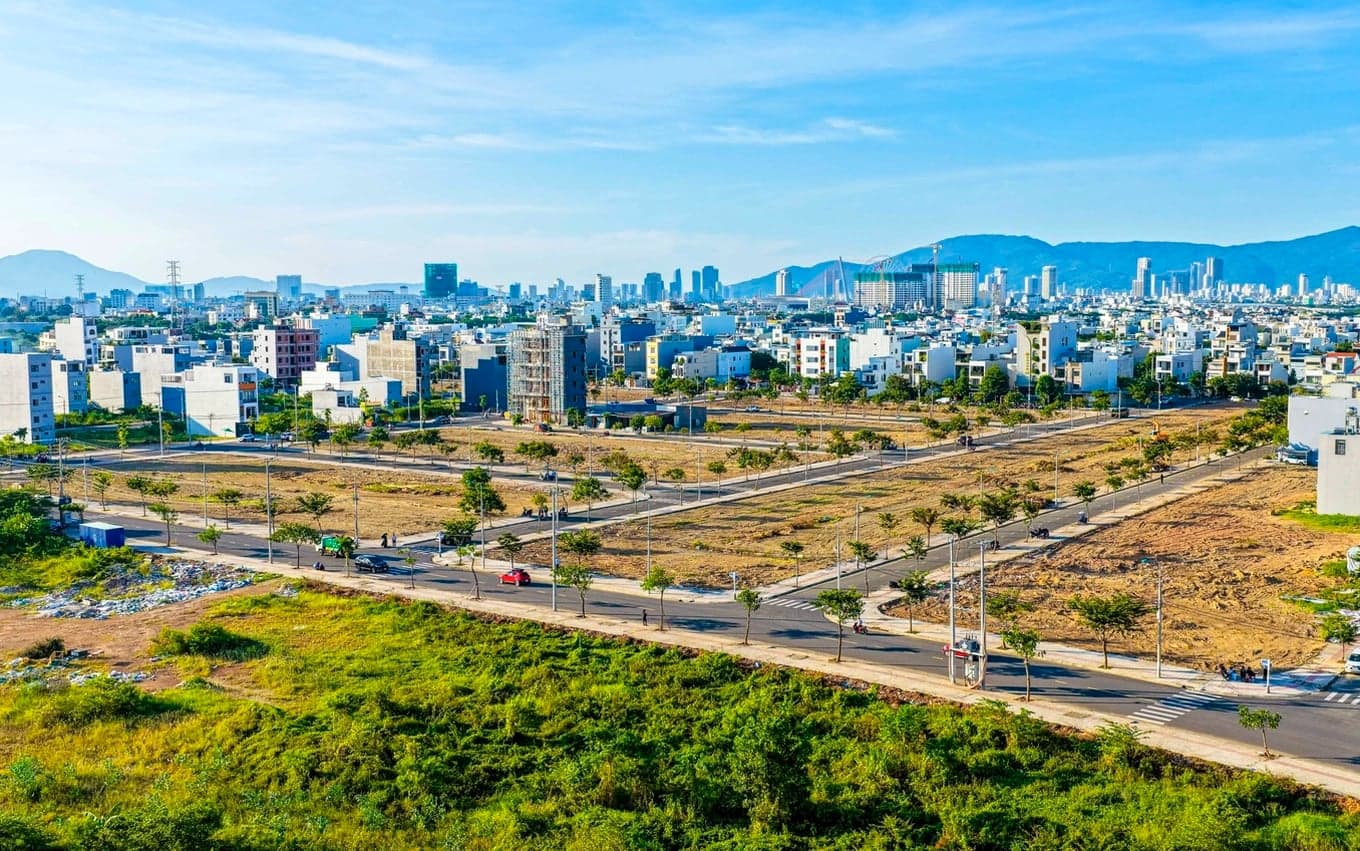
According to DKRA Consulting's third-quarter housing market report for Da Nang, real estate liquidity remains under pressure as buyers stay cautious because of high interest rates. Primary land supply reached 1,547 plots across seven projects, but new supply accounted for about 4%. The market recorded only 54 transactions, equal to 4% of total supply and 16% fewer than in the previous quarter.
Weak demand has started to push prices down. Primary land prices fell about 7% quarter on quarter, while secondary prices declined by an average of 3% as some investors cut prices to recover capital. Developers also increased discounts and offered easier payment terms. Primary prices were about VND45.6–61.6 million per square metre in Hoi An Dong, VND29.3–47 million in Hoi An Tay, and VND17.4–26 million in Dien Ban Dong.
Apartment sales in Da Nang also declined. Primary supply reached 4,385 units across 20 projects, down 14% from the previous quarter, while new supply fell by nearly 40%.
The market sold 2,099 apartments, down 25% quarter on quarter and 24% year on year. Class B apartments made up 46% of supply and 68% of sales. Most transactions were in newly launched projects, where prices were about VND60–70 million per square metre. Secondary prices fell 3–5% as leveraged investors faced cash-flow pressure.
The market is not expected to improve quickly. In the fourth quarter, Da Nang may see only 50–100 new land plots and about 500–1,000 new apartments offered for sale.
DKRA Consulting expects land demand to remain weak in the short term. Primary prices may stay high, while secondary prices could fall further because of borrowing costs and the need to recover capital. Apartment demand is also unclear while interest rates remain high and property credit is controlled. The market may recover in the fourth quarter, but the improvement is expected to remain limited, without a sharp rebound.
Demand fell even more sharply in Ho Chi Minh City and nearby areas. Primary apartment supply in the third quarter exceeded 13,200 units, down 31% from the previous quarter, with about 94% located in Ho Chi Minh City. New supply exceeded 4,000 units, but sales fell 66% from the second quarter as buyers waited amid high borrowing costs and tighter property credit controls.
With liquidity weak, developers are supporting buyers through sales policies rather than large cuts to listed prices. The report says most developers continue to expand discounts for scheduled or early payments, extend principal and interest grace periods, and use other measures. These steps indirectly reduce effective primary prices and are intended to improve market liquidity.
Primary land supply in Ho Chi Minh City and nearby areas rose 1%, but about 95% came from projects launched earlier. New supply fell 30%, while sales declined about 66% from the second quarter.
The fourth quarter may bring 200–300 new land plots and 7,000–10,000 apartments to market. Supply will focus on eastern and southern Ho Chi Minh City and the former Binh Duong province. Demand may improve toward the end of the year as housing needs rise, but DKRA Consulting says a sharp short-term increase is unlikely while buyers remain under interest-rate pressure.
Le Hoang Lan Nhu Ngoc, senior director and head of strategic consulting at Cushman & Wakefield Vietnam, told Dân trí that there is not yet enough basis to say the apartment market is entering a broad price-cutting cycle. With prices in central areas already above VND100 million per square metre, land, site clearance, borrowing, labour, materials, and handover standards make it difficult for developers to cut listed prices.
Actual prices may still be adjusted through sales policies. Instead of cutting prices directly, developers are likely to increase discounts, subsidize interest, extend grace periods, and reduce initial payment requirements. This is described as a technical price adjustment that can stimulate demand while keeping listed prices unchanged.
Future demand will depend heavily on interest rates. With floating rates of 12–14%, many owner-occupier buyers are delaying decisions, waiting for more affordable borrowing costs and choosing projects that fit their finances.
It is too early to conclude that the market has entered a broad price-cutting cycle. However, several experts say it is going through a selection process, with greater pressure on projects whose prices do not match real demand. Future price movements will depend on interest rates, the pace of new-supply absorption, and the mood of owner-occupier buyers.
Sources: Dân Trí

